Change Your Mind
In the infinite hostility of outer space, there lies an exception. A miracle planet. A cradle of life, with unlimited potential. But greed and ambition have raged like a plague, and an insatiable lust for power and control now threatens to extinguish all natural life on the planet. Life doesn’t have to be this hard. All of society’s problems are man-made. History has been hijacked by a psycho-pathetic elite of self-infatuated children. Our economic and money systems have been used for centuries to capture public creativity and talent and to steal our collective productivity. We don’t have to accept and obey our leaders. We don’t have to merge our lives with the dominant culture.
Debt-based money is the primary control mechanism that captures and controls us. Upfront financing encumbers assets with liabilities before they are even created. Demanding upfront payment of the entire depreciation cost of expensive capital assets like homes and vehicles, from average income workers whose savings can’t possibly cover the cost, creates a perpetual need for debt which only benefits lenders. Likewise, adding profit, an imaginary subjective amount to the cost of everything, which was never paid out in external costs to the marketplace, leaves workers short of the asking price for the goods and services that they produced while working. This too creates a need for debt which is a complimentary source of imaginary new money. Profit and debt are two sides of the same coin, the same trap, that no one is allowed to talk about.
This video describes a way out of the debt money game that has been played against us, virtually unchanged, for centuries. Debt has created a financial tipping point, and technological progress has created an environmental tipping point. Civil society is about to self-destruct. We must stop wasting our intelligence and squandering the gifts of Creation, our human and natural resources. Here is how we can do it.
The purpose of money should be to facilitate a fair trade of the time and energy that it takes to produce goods and services and operate a society. Since natural resources are provided by Creation for free, labour time is the only real cost of everything produced. All of the other input and operating costs of production are really just bundles of labour and natural resources that are traded in a particular shape or form.
New money is necessary to represent the value of new assets each time they are created. As assets are used and wear out, a portion of the money created to represent their value must be extinguished. In this way, the money available for consumption always matches the remaining asset value exactly.
Productivity itself creates new money instantly. Producers don't need to wait for sales to generate income. The time spent working rewards workers instantly. Employers don't need upfront cash for payrolls. Work itself pays workers for working. Banks, government and corporations no longer create new money or credit. Only workers do. Money does not recirculate. Once it is spent on final consumption it is extinguished. Businesses cannot re-spend the labour credits of others that are extinguished by sales. Upon approval of their business plan at a local credit office, each business is given a commercial line-of-credit account to record and manage their trade transactions. A credit limit is set to ensure no one is scamming the system.
Consider this example. A lumberjack is cutting trees and collecting logs. The trees are provided freely by Creation so there is no raw material cost. The only costs are the lumberjack's own labour hours, his fuel and a small depreciation cost for his equipment. At the end of each day, the lumberjack reports his hours to his local credit bank and his commercial line-of-credit is adjusted. The amount available to spend increases immediately. He does not have to wait until he sells his logs for income. The value and price of his logs equals his costs. No mark-up or profit is added to the price.
So to recap, the natural resources are free, the lumberjack has been paid and his operating expenses and equipment depreciation costs have been added to the price of the logs. Since the lumberjack has already been paid for producing the logs, he has no legitimate claim of ownership for the logs which were originally created by nature. The lumberjack is merely the custodian of a public good that was created by nature for all to enjoy.
At a planing mill the logs are converted into lumber. The logs are transformed at the mill, not consumed, so their value is not depreciated. The price of the logs is added to the mill's custodial line-of-credit and subtracted from the lumberjack's. The mill requires no upfront money to acquire the logs. The transfer is an accounting transaction only, and the mill is now the custodian of the logs.
Like the lumberjack, the workers at the mill earn the hours they work each day instantly as income. New credits are created and added to their bank accounts and no upfront cash is needed to pay them. The miller adds his own company's labour costs to the price of the logs plus his overhead, depreciation and operating costs. Like the lumberjack, the miller as no legitimate claim of ownership for the wood which was originally created by nature.
All of the miller’s costs have been added to the custodial line-of-credit when the lumber is transferred to the lumber retailer. Again no upfront cash is required. The value received by the retailer is simply added to his custodial line-of-credit while the miller's outstanding credit balance is reduced by an equal amount.
The lumber retailer provides a distribution service for the product. No consumption or depreciation in value occurs. The retailer adds his own costs to the price of the lumber and sets the final retail selling price. The retailer has 2 types of customers. Businesses and consumers. Lumber transferred to another business to be used as a component in the creation of a new product or service is recorded using a cashless, commercial, line-of-credit just like the lumberjack or the mill. A construction company would need no upfront cash to order materials or pay for asset transfers of production inputs. Custodial lines-of-credit would simply be adjusted.
End-users who actually consume lumber for their own purposes must pay upfront for the wood they use. If their consumer credit account is insufficient to pay the full price then the transaction will not be completed. There are no longer consumer lines-of-credit to fuel personal consumption of most items. Consumers can only spend income they already earned by working and contributing to society.
The only exception to this involves the transfer and use of major assets like homes and vehicles. Major consumer assets are financed using the depreciation rate specified by the asset producer. For example, a house designed and built to last 100 years would be depreciated at the rate of twelve hundred equal monthly payments. Vehicles and expensive equipment built to last 20 years would be paid for in 240 equal payments. No debt or interest would be involved. End-users would simply pay the actual asset depreciation cost that their usage caused.
Every day items that are fully consumed in less than a year like food, and inexpensive items that cost less than 100 hours like clothing, houseware and most furniture and appliances would be priced at 100% of their full cost.
Items used by many people simultaneously like live performances and events, books, audio and video recordings would use adjustment pricing that continuously divides total cost by the number of simultaneous users and adjusts individual prices accordingly.
For example, the cost of seats at a concert or hockey game would decrease as more people buy tickets. No one would be charged until the final number of attendees was determined. People could monitor the seat cost in real time and buy-in or cancel purchases anytime before the actual performance time. All people would pay the same price for their seat regardless of when they bought-in, and no one would be charged until the event actually began. Higher pricing for premium seat locations could still be calculated and applied.
It is difficult to predict how much the price of almost everything people purchase will drop. Corporate costs are dark trade secrets protected by intellectual property rights and patents. Once you understand how costs along the chains of profit and debt compound and bind prices to ridiculous calculations of value, you will feel the sucker punch of economic stupidity. We’ve been had for generations, our minds clouded by false beliefs, purposefully programmed to keep us dependent and weak while the rich grow ever more powerful.
Its time to break the spell they have cast and burst the illusions they create to divert our attention. They have no legitimate authority to rule over us or make laws that bind us in financial servitude. We already run the economy and produce everything made. We don’t need the rich or government to live, but without us they have nothing but debt.
Spread the news of this video far and wide and watch the other videos in this series that describe specific strategies to break free from their grip. They are tightening the screws on us and the end of the free world is near. Will you go quietly into the darkness, or light a lamp to lead others to a better world?
The Myth of Freedom
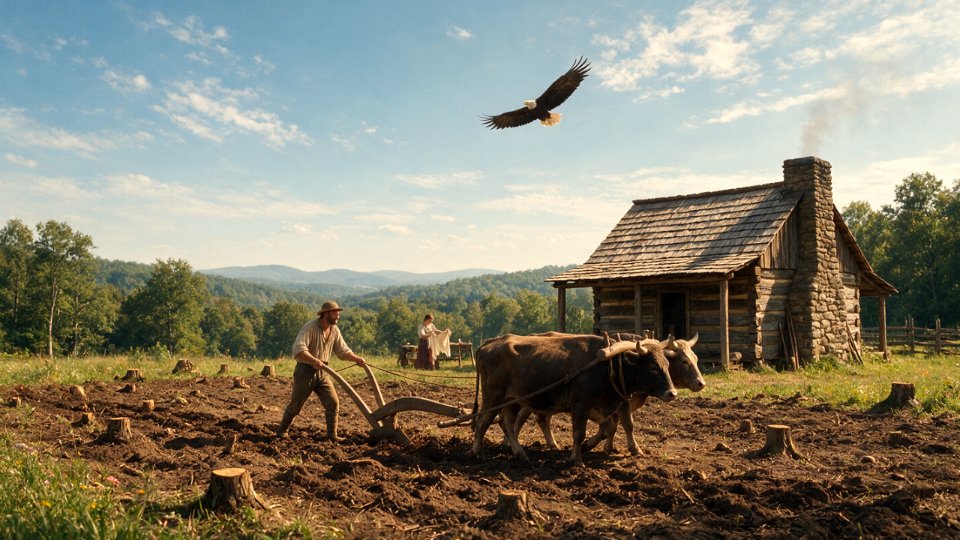
From 1750 to 1850, American homesteaders—especially those moving westward after the Revolution—needed to acquire a range of essential goods and services to establish and maintain their farms.
While many items were produced on-site through subsistence farming, critical tools, materials, and services had to be purchased or bartered from external producers, often at great expense and logistical difficulty.
Essential Goods and Supplies
Homesteaders required a variety of physical goods to build homes, cultivate land, and sustain their families:
• Farm Tools and Equipment: Plows (notably the steel-faced plow introduced by John Deere in 1838), hoes, axes, scythes, and later, improved devices like James Oliver’s “chilled plow” in the 1860s.
• Livestock: Horses, oxen, cows, chickens, and pigs were essential for labor, food, and breeding.
• Building Materials: Lumber, nails, glass, and hardware for constructing homes, barns, and fences. Early settlers often used sod due to lack of timber.
• Household Goods: Cast-iron stoves, cookware, oil lamps, textiles, and furniture.
• Seeds and Fertilizer: Necessary for crop cultivation; often had to be bought when local supplies were insufficient.
• Food Staples: While many grew their own corn, beans, and wheat, items like salt, sugar, coffee, and spices were typically purchased.
Key Services and Infrastructure
In addition to tangible goods, homesteaders depended on several critical services:
• Transportation: Wagons and later railroads were vital for moving supplies in and crops out. Before the expansion of rail networks, transportation was slow and costly.
• Blacksmithing: Essential for repairing tools, shoeing horses, and fabricating metal parts.
• Mill Services: Grain mills were needed to process corn and wheat into flour.
• Banking and Credit: Farmers often borrowed money to buy land, tools, and livestock, relying on banks despite high interest rates.
• Medical Care: Though often limited, some settlers paid for doctors or midwives, especially during childbirth or illness.
Who Produced These Goods and Services?
The production of these goods and services came from a mix of local artisans, emerging industries, and distant manufacturers:
• Local Blacksmiths and Carpenters: Provided custom tools, repairs, and construction help within frontier communities.
• Eastern and European Manufacturers: Many finished goods like stoves, textiles, and advanced farm tools were produced in industrializing regions of the Northeast or imported from Europe.
• Merchants and General Stores: Acted as intermediaries, selling goods brought in via wagon trains or, later, railroads.
• Banks and Financial Institutions: Mostly located in towns and cities, these provided loans and credit, though often at prohibitive rates for small farmers.
• Railroad Companies: By the mid-19th century, railroads became crucial in transporting both people and goods, though they initially charged high freight rates.
Economic Challenges for Homesteaders
Despite the availability of land—especially after the Homestead Act of 1862 (just after this period)—the cost of starting a farm was steep.
It could take close to $1,000 to purchase the necessary supplies, a significant sum when most families lived hand-to-mouth.
Many would-be landowners ended up as migrant laborers, working for wages on larger farms because they couldn’t afford the startup costs.
Moreover, market forces often worked against small farmers. As more settlers produced crops, prices fell, while the cost of borrowed money and transported goods remained high.
This economic pressure contributed to the rise of large “bonanza farms” and fueled agrarian unrest later in the century.
The image of the early American settler as a completely self-sufficient, independent yeoman is largely a myth.
While homesteaders were indeed industrious, their survival and economic viability were deeply entangled with credit networks, merchants, and market dependencies from the very beginning.
The Myth of Independence
The romanticized notion of the self-reliant pioneer obscures the reality that even the earliest settlers required capital, credit, and external goods to establish a farm.
As historian William Chauncy Langdon noted, "if you don’t bring some implements to get started, it’s not homesteading; it’s camping." From axes and plows to seeds and cookware, essential tools had to be purchased or bartered, tying settlers immediately to a cash or credit economy.
Dependency on Credit and Merchants
Credit was the lifeblood of colonial and early American frontier economies.
Studies of merchant account books from the 18th century show that over 98% of purchases in places like Connecticut and Massachusetts were made on credit, not with cash or barter. Settlers relied on:
• Book Credit: Local merchants extended credit to farmers, who paid back debts after harvest.
• International Credit: Colonial merchants depended on credit from British suppliers to stock their shelves.
• Crop Liens: In later decades, especially after the Civil War, merchants held legal claims on future harvests as collateral for credit.
This system meant that financial privilege—or at least access to a trustworthy merchant—was often the difference between success and failure.
High Startup Costs and Economic Barriers
Establishing a farm was expensive.
In 1843 Illinois, the cost to buy, fence, and improve just 80 acres of land was nearly $1,278, excluding the cost of livestock and tools.
Adding a pair of oxen, a wagon, and basic implements could push total startup costs well over $1,500—a prohibitive sum for most families without savings or credit.
Many would-be homesteaders could not afford these costs and instead became tenant farmers or migrant laborers, working for wages on larger estates. This economic stratification demonstrates that land ownership was not equally accessible; it favored those with capital or strong credit connections.
The Central Role of the General Store
The general store was more than a shop; it was the economic and social hub of frontier life.
Storekeepers acted as:
• Bankers: Extending credit and tracking debts in ledger books.
• Merchants: Supplying goods that couldn’t be produced on-site (e.g., salt, coffee, nails, textiles).
• Community Leaders: Mediating disputes, delivering news, and connecting isolated families to the wider world.
For many settlers, the general store was their only link to the market economy, reinforcing their dependency on external suppliers just as modern consumers rely on global supply chains.
Far from being isolated islands of self-sufficiency, early American homesteaders were deeply embedded in economic networks of credit, trade, and dependency.
Access to land and resources was heavily influenced by finance and privilege, challenging the myth of the wholly independent pioneer.
Their reality mirrors modern economic interdependence, where survival and success depend on access to capital, supply chains, and community infrastructure.
For many, the shift from feudal bondage to market dependency was a change in the mechanism of control, not necessarily the degree of freedom. While legal status changed, economic coercion often replicated the constraints of serfdom.
Economic Coercion vs. Physical Coercion
The primary distinction between the frontier and feudalism lies in the method of enforcement. Feudal serfs were bound by law and physical force; they could not leave the land without permission.
In contrast, homesteaders were legally free but bound by debt and economic necessity.
However, historians argue this distinction is often negligible in practice. The crop-lien system (prevalent post-Civil War but rooted in earlier credit practices) trapped farmers in cycles of debt where they effectively worked for merchants rather than themselves.
Like serfs, they could not leave without forfeiting their livelihood, and their labor's value was dictated by creditors who set both the price of supplies and the value of the crop. This created a state of debt peonage, where the "freedom" to contract masked a reality of economic enslavement.
Manipulation of Labor Value
Market control over prices meant a loss of autonomy over the value of one's labor. In a "free market" dominated by monopolies (e.g., a single general store or railroad), prices were not negotiated but dictated.
• Price Fixing: Merchants often inflated the cost of goods while depressing the price paid for crops, capturing the surplus value of the farmer's labor.
• Interest as Rent: High interest rates on credit functioned similarly to feudal rent, extracting wealth from the producer without their consent to the terms.
• Lack of Alternatives: With no competing buyers or sellers, the "freedom" to choose was illusory. The farmer had to accept the terms offered or starve.
This dynamic mirrors the feudal relationship where the lord controlled the mill, the oven, and the market, ensuring the peasant remained subservient regardless of their legal status.
The Illusion of Mobility
Proponents of the frontier myth argue that settlers could simply move west if conditions were unfavorable. However, this "safety valve" required capital—money for wagons, tools, and new land. For those already in debt, mobility was impossible. Just as serfs were tied to the land by law, indebted homesteaders were tied by financial obligation. The threat of foreclosure, loss of equipment, or legal action (including imprisonment for debt in earlier periods) served as a powerful deterrent to leaving, effectively binding them to their creditors
Conclusion
If freedom is defined as control over the fruits of one's labor, then the distinction between a serf bound by law and a farmer bound by debt is indeed slim.
Both systems concentrated power in the hands of a few (lords or merchants) who dictated the terms of survival. The frontier did not eliminate hierarchy or exploitation; it merely privatized it, replacing the lord's whip with the banker's ledger. In this view, the "free market" was not a realm of liberty but a new architecture of control, where financial privilege replaced hereditary title as the determinant of power.